There are certain numbers in financial markets that immediately make people sit up and take notice. For me, $100 a barrel is one of them.
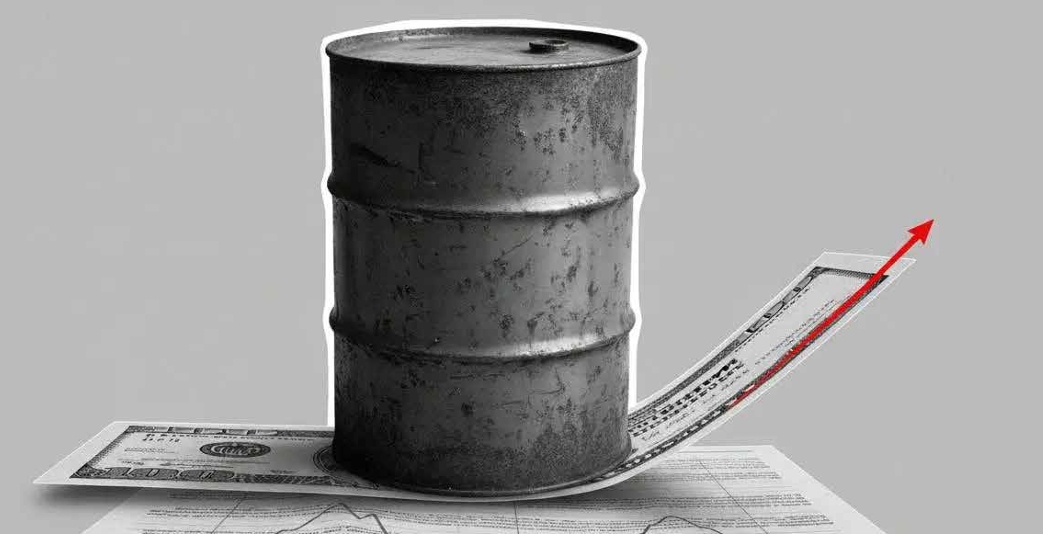
Brent crude has pushed back above $100 this week for the first time since July, as the conflict involving the US and Iran has intensified and concerns have grown over the security of oil supplies through the Middle East. Brent briefly reached around $100.19 on Wednesday, while WTI moved above $94.
At first glance, I think it is tempting to treat this as just another geopolitical story. Another day, another headline, another oil price spike. But I think investors would be making a mistake by looking at it that way.
Oil is not simply another commodity. It sits underneath an enormous part of the global economy. Transport, aviation, manufacturing, shipping, agriculture, chemicals and even the cost of getting products from one side of a country to another are all a ected by energy prices.
That is why I think $100 oil deserves considerably more attention than the headline number might suggest.
The $100 Question
The really important question, in my view, is not whether oil reaching $100 is psychologically significant. Clearly it is. The more important question is whether it stays there.
There is a huge di erence between oil briefly touching $100 because markets panic about a geopolitical event and oil remaining above $100 for months because supplies have been genuinely disrupted.
Markets can generally cope with a temporary shock. What they struggle with is a persistent increase in the cost of something as fundamental as energy.
That is what concerns me about the latest move. The conflict has intensified, attacks have threatened energy infrastructure and shipping through the Strait of Hormuz has fallen dramatically. Reuters reports that only six commodity vessels passed through the strait on Tuesday, compared with a normal level of roughly 125 commercial vessels a day before the conflict. Hormuz normally handles around 20% of global crude oil and LNG supplies.
I think that is far more important than the psychological significance of seeing a three digit oil price.
The market is beginning to price in the possibility that this disruption lasts.
Oil Has A Nasty Habit Of Finding Its Way Into Everything
The obvious impact is petrol. If crude oil becomes substantially more expensive, eventually filling up the car becomes more expensive too. That a ects households directly, particularly people who drive significant distances for work or rely heavily on their cars.
But petrol is only the beginning.
Airlines face higher fuel costs. Shipping companies face higher transportation bills. Manufacturers face higher energy costs. Businesses moving products around the country face higher expenses.
Even products which appear to have very little connection to oil can be affected.
Food is a good example. Farmers use fuel and fertiliser. Food manufacturers require energy. Supermarkets transport enormous quantities of products. Packaging and chemicals are also heavily connected to the energy industry.
This is why I think investors sometimes underestimate the importance of oil. It is not just the price at the petrol station. It is a cost that can work its way through the entire economy.
And Then There Is Inflationt
This is where the story becomes much more uncomfortable. For much of the last year, investors have been hoping that the inflation problem was gradually becoming yesterday’s problem. Central banks raised rates, economies slowed and inflation came down significantly from its post pandemic highs. Now oil is threatening to complicate the process all over again. If energy prices remain elevated, inflation can become more persistent. That creates an awkward problem for central banks because they have very little control over the initial cause.
I think this is particularly important for the Bank of England. UK inflation is already proving stubborn, and economists surveyed by Reuters now expect Bank Rate to remain at 3.75% through the end of 2026 and into at least the middle of 2027, partly because higher energy prices have pushed back expectations for rate cuts. Personally, I think this is a good example of why investors should never become too comfortable with forecasts about interest rates. A few months ago, the conversation was largely about when rates would come down. Now the conversation is increasingly about whether central banks can a ord to cut them at all.
The Central Banks Have A Problem
Central banks are generally quite good at influencing demand. They can raise interest rates to make borrowing more expensive and slow spending, or cut rates to encourage investment and economic activity. What they cannot do is produce more oil. If inflation is rising because consumers are spending excessively, higher interest rates can help. If inflation is rising because a major oil producing region is experiencing a serious disruption, monetary policy has a much less obvious answer. Raising interest rates will not make another tanker appear in the Strait of Hormuz. It will not repair an oil facility and it will not end a military conflict. It will, however, make mortgages more expensive, increase corporate borrowing costs and potentially slow economic growth. That is why I think the real danger is not simply higher oil prices. It is the combination of higher inflation and weaker growth. That is the environment investors tend to dislike most.
Some Companies Lose. Others Win.
One thing I have learned from watching markets over the years is that there is rarely a completely negative story. Oil above $100 is obviously good news for some businesses. Energy producers can benefit significantly from higher prices, particularly companies with strong production economics and relatively low operating costs. Oil service companies can also benefit if producers respond to higher prices by increasing investment. Further down the chain, however, the picture becomes more complicated. Airlines are obvious losers because fuel represents one of their largest costs. Transport companies face pressure. Manufacturers can see their margins squeezed. Businesses operating on thin margins may struggle to pass higher costs on to customers. That is why I think investors should be looking beyond headline earnings forecasts. I would much rather know how exposed a company is to energy prices, how much debt it carries and how much pricing power it has than simply look at whether analysts expect earnings to increase next year. In an uncertain environment, the quality of the cash flow matters.
This Is Where Cash Flow Becomes Important
This is probably the part of the current environment that interests me most from an investment perspective. When everything is going well, markets tend to reward exciting growth stories. Investors are happy to pay high valuations for businesses promising enormous profits several years into the future. When oil is above $100, inflation is proving stubborn and interest rates are uncertain, I think investors naturally become more interested in something rather less glamorous. Cash. Not the cash sitting in a bank account, necessarily, but businesses and investments that actually produce reliable cash flow. Personally, I think this is one of the most underrated qualities in investing. A company that generates predictable cash, has manageable debt, strong customers and the ability to pass some higher costs on to customers may not be the most exciting investment in the world. But when the economic environment becomes unpredictable, I think those characteristics become extremely valuable.
The Return Of Income
There is another reason I think the current environment is particularly interesting. For years, investors were e ectively forced towards equities because traditional fixed income oered very little. When interest rates were close to zero, earning a meaningful return from relatively defensive assets was di cult. That world has changed. Government bonds and other forms of fixed income can now oer meaningful yields, while investors are also finding more opportunities to generate income from businesses and assets with established cash flows. I do not think this means investors should suddenly abandon equities. Far from it. But I do think the days when investors could simply chase growth and ignore income are looking increasingly distant. When uncertainty rises, being paid to wait becomes rather attractive.
What About Gold?
Then there is gold. Gold has also attracted significant investor interest as geopolitical tensions have increased, with the metal trading around $4,400 an ounce this week. I understand the attraction. Gold has no earnings forecast to disappoint, no chief executive to worry about and no quarterly profit warning. In an environment of geopolitical uncertainty, inflation concerns and nervous financial markets, investors naturally look for assets they believe can provide protection. But I think there is an important distinction between protection and income. Gold can potentially protect capital in certain environments, but it does not pay you to hold it. That does not make gold bad. It simply makes it di erent. In my view, a sensible portfolio should not necessarily ask which single asset will perform best. It should ask what combination of assets can provide growth, income, liquidity and protection across di erent economic environments.
The $100 Barrel Is A Warning
I do not think investors should look at $100 oil and immediately predict another global crisis. Oil has been above $100 before. Economies adapt. Consumers change their behaviour. Producers respond to higher prices. Alternative supplies emerge and demand can eventually weaken. The important question is what happens next. If oil quickly falls back towards previous levels, this week’s move may eventually look like another geopolitical scare that briefly rattled markets. If oil remains above $100 for an extended period, however, I think the consequences could be considerably more serious. Inflation could prove stickier. Interest rate cuts could be delayed. Consumers could have less disposable income. Corporate margins could come under pressure and investors could start demanding higher returns for taking risk. That is when the $100 oil story becomes much bigger than oil.
The Investor’s Lesson
Personally, I think one of the biggest mistakes investors can make is becoming too attached to the economic environment they have become accustomed to. For years, we had incredibly cheap money, low inflation and enormous enthusiasm for technology and growth stocks. It was a wonderful environment for certain types of investment. But markets change. Oil changes. Interest rates change. Inflation changes. Geopolitics changes. Investor psychology changes. The important thing is not to predict every change correctly. I have never believed that was realistic. Instead, I think the sensible approach is to build a portfolio that can cope when the forecast turns out to be wrong. That might mean owning businesses with genuine pricing power. It might mean holding assets that generate reliable income. It might mean maintaining some liquidity. It might mean having exposure to commodities or other forms of protection. What I would be wary of is assuming that yesterday’s winning strategy will automatically remain tomorrow’s winning strategy.
The Bigger Picture
Oil above $100 is ultimately a reminder that the global economy remains remarkably vulnerable to events that investors cannot control. A conflict thousands of miles away can change the price of petrol. The price of petrol can influence inflation. Inflation can influence interest rates. Interest rates can influence mortgages, company borrowing and share valuations. That chain reaction can happen surprisingly quickly. I think that is why this week’s oil move matters. It is not because $100 is some magical number that suddenly changes the world. It is because it reminds us how interconnected financial markets really are. Only recently, investors were debating when interest rates would fall, whether inflation had finally been defeated and whether cheaper money would return. Now oil is above $100 again, central banks are having to reconsider the path ahead and investors are once again being reminded that inflation has not completely disappeared. My view is fairly simple. I would rather own investments that can withstand an unpleasant surprise than investments that only work if everything goes according to plan. Oil has just given investors another unpleasant reminder of why that matters. And if the price stays above $100 for much longer, I suspect it will not be the last one.
This article is a personal opinion piece for general information and does not constitute financial, tax, or property advice. Property and rental markets vary significantly by location, and individual circumstances (cash purchase vs mortgaged, limited company vs personal ownership, portfolio size) materially change the analysis above. If you’re considering selling or restructuring a rental property, speak to a qualified accountant or financial adviser.